Brent Campaign Triggers Shift in UK Gambling Policy Approach
Written by Ellis Powell · Aug 31, 2026
Brent Campaign Triggers Shift in UK Gambling Policy Approach
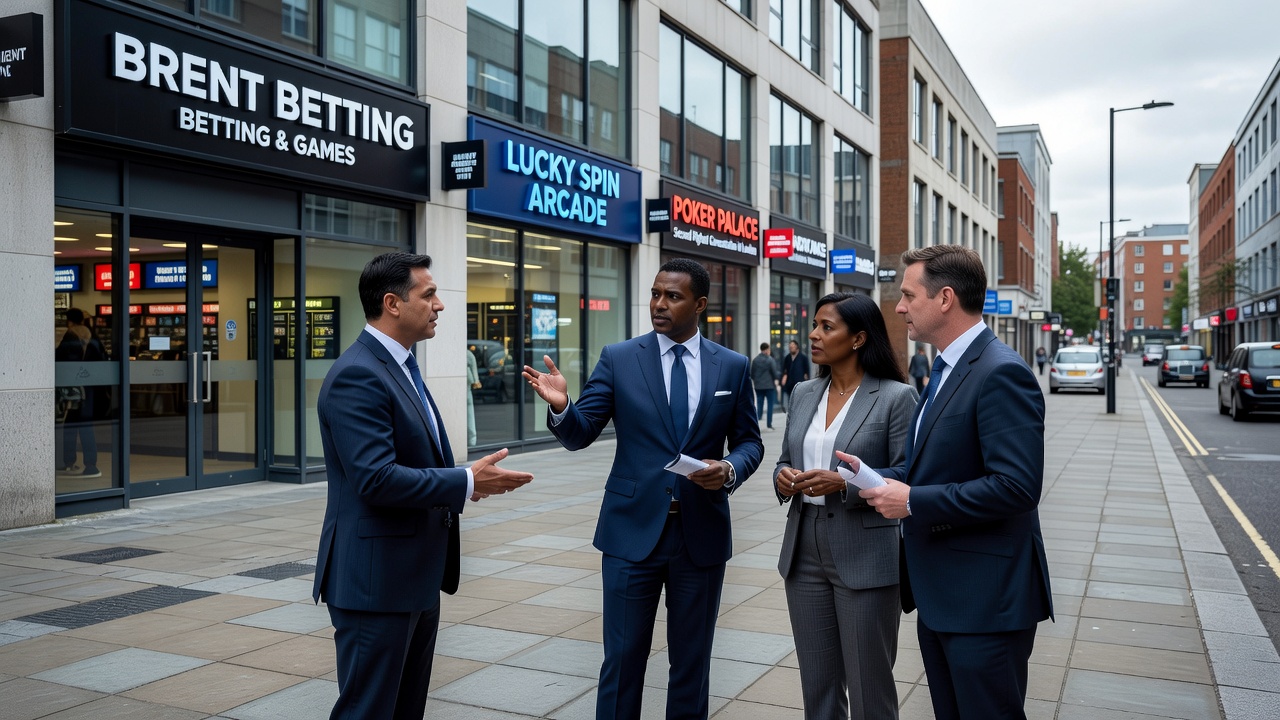
Local politicians in Brent, north-west London, have long pushed back against the concentration of betting shops and slot arcades in their borough, and their sustained efforts contributed directly to the UK government scrapping its “aim to permit” policy earlier in August 2026; Brent ranks second in London for the density of such premises, which gave those campaigns particular visibility at the national level. Observers note that this single borough’s resistance helped tip the balance against a regulatory framework that had previously sought to balance commercial interests with consumer protections, and the policy reversal marks a clear departure from earlier government positions.
Brent’s Role in the National Conversation
Campaigns in Brent focused on the visible clustering of betting outlets along high streets, where residents reported increased foot traffic tied to gambling venues and associated social pressures; elected officials there gathered evidence from local businesses and community groups, then presented those findings to parliamentary committees and regulatory bodies. Data indicates that such concentrated premises can strain neighborhood resources, and Brent’s representatives argued successfully that the previous “aim to permit” stance had not accounted for these localized effects. The government’s decision in August 2026 to abandon that approach therefore reflected years of accumulated local feedback rather than any sudden national shift.
Steady National Decline in Betting Shop Numbers
Across the UK, betting shop totals have fallen consistently since their 2012 peak of 9,128 outlets, reaching 5,789 by 2025, and this downward trajectory continued even before the policy announcement; operators have cited a combination of regulatory tightening, rising operational costs, and changing consumer habits as the main drivers. Recent closure notices from Betfred and Evoke illustrate the pattern, with both companies reducing their physical footprints in response to the same pressures that local authorities like Brent have highlighted. Adult Gaming Centre numbers, meanwhile, have plateaued after earlier reductions, suggesting that the broader retail gambling sector faces a period of stabilization rather than outright contraction in every category.
Regulatory and Economic Pressures on Operators
Betfred and Evoke each announced further site reductions in the months leading up to the August 2026 policy change, citing compliance costs and slower footfall as key factors; these moves align with the national statistics that show a loss of more than 3,300 betting shops over roughly thirteen years. While the “aim to permit” framework had once encouraged measured expansion under strict licensing, its removal signals that future applications will face closer scrutiny, particularly in areas already saturated with premises. Those who track industry filings note that economic pressures alone do not explain every closure, since local planning objections have also increased in frequency and success rate.
Political and Reputational Challenges Ahead
The retail gambling sector now confronts heightened political attention at both local and national levels, with Brent’s experience serving as a template for other councils considering similar restrictions; reputational concerns have grown as well, because repeated media coverage of clustered betting outlets has shaped public perceptions. Figures reveal that the steady numerical decline since 2012 has not eliminated political friction, and the August 2026 decision removes one argument operators previously used to defend new openings. Observers point out that future licensing hearings will likely reference Brent’s campaign outcomes, giving local authorities additional leverage when weighing applications against community impact data.
Looking Forward for Retail Gambling Premises
With the “aim to permit” policy now off the table, operators must adapt to a regulatory environment that places greater weight on local objections and cumulative impact assessments; the plateau in Adult Gaming Centre numbers suggests that some segments of the market have already adjusted to tighter conditions. Data on premise density continues to inform debates in Westminster, and Brent’s second-place ranking in London keeps that borough’s experience central to those discussions. The combination of falling shop counts and the August 2026 policy reversal therefore sets the stage for a period in which political engagement, rather than expansion plans, will dominate industry strategy.
Conclusion
The sequence of events that began with sustained local campaigns in Brent and ended with the national policy change in August 2026 demonstrates how individual borough actions can influence wider regulatory direction; national statistics on betting shop reductions and operator closures provide the broader context, while reputational and political pressures continue to shape the sector’s outlook. Those following these developments will watch how other councils apply the lessons from Brent when reviewing their own licensing decisions in the months ahead.